

Over the past few years, the liquid alternatives space has moved decisively into a new ETF era.
What was once a narrow category now stretches from CTA to hedge-fund replication strategies, sometimes pairing those return streams directly with core stocks and bonds exposures.
And thanks to their low-cost, daily liquidity and ease of access, these vehicles are attracting progressively more inflows. As the category has grown, however, so has a persistent criticism regarding their investable universe.
Notoriously, ETFs are designed for maximum scale and capacity, which limits their ability to access the more niche markets that many CTAs actively trade. To some investors, this constraint is significant enough to make ETFs suboptimal vehicles for gaining exposure to trend and other alternative strategies.
Today, we demonstrate that these concerns are largely unfounded and that trend-following programs, even when delivered through “compact” ETF structures, can provide meaningful diversification benefits to traditional (beta-heavy) portfolios.
Disclosure - We do not endorse or sponsor any asset manager, ETF, or fund provider. All opinions expressed in this article are our own and do not constitute investment advice. The analysis is provided for informational and research purposes only.

A Simple Trend Program
We begin by designing a plain-vanilla trend program. Importantly, it should not be seen as a ready-to-trade portfolio, but as a generic baseline that will be shared by all simulations.
Futures Universe
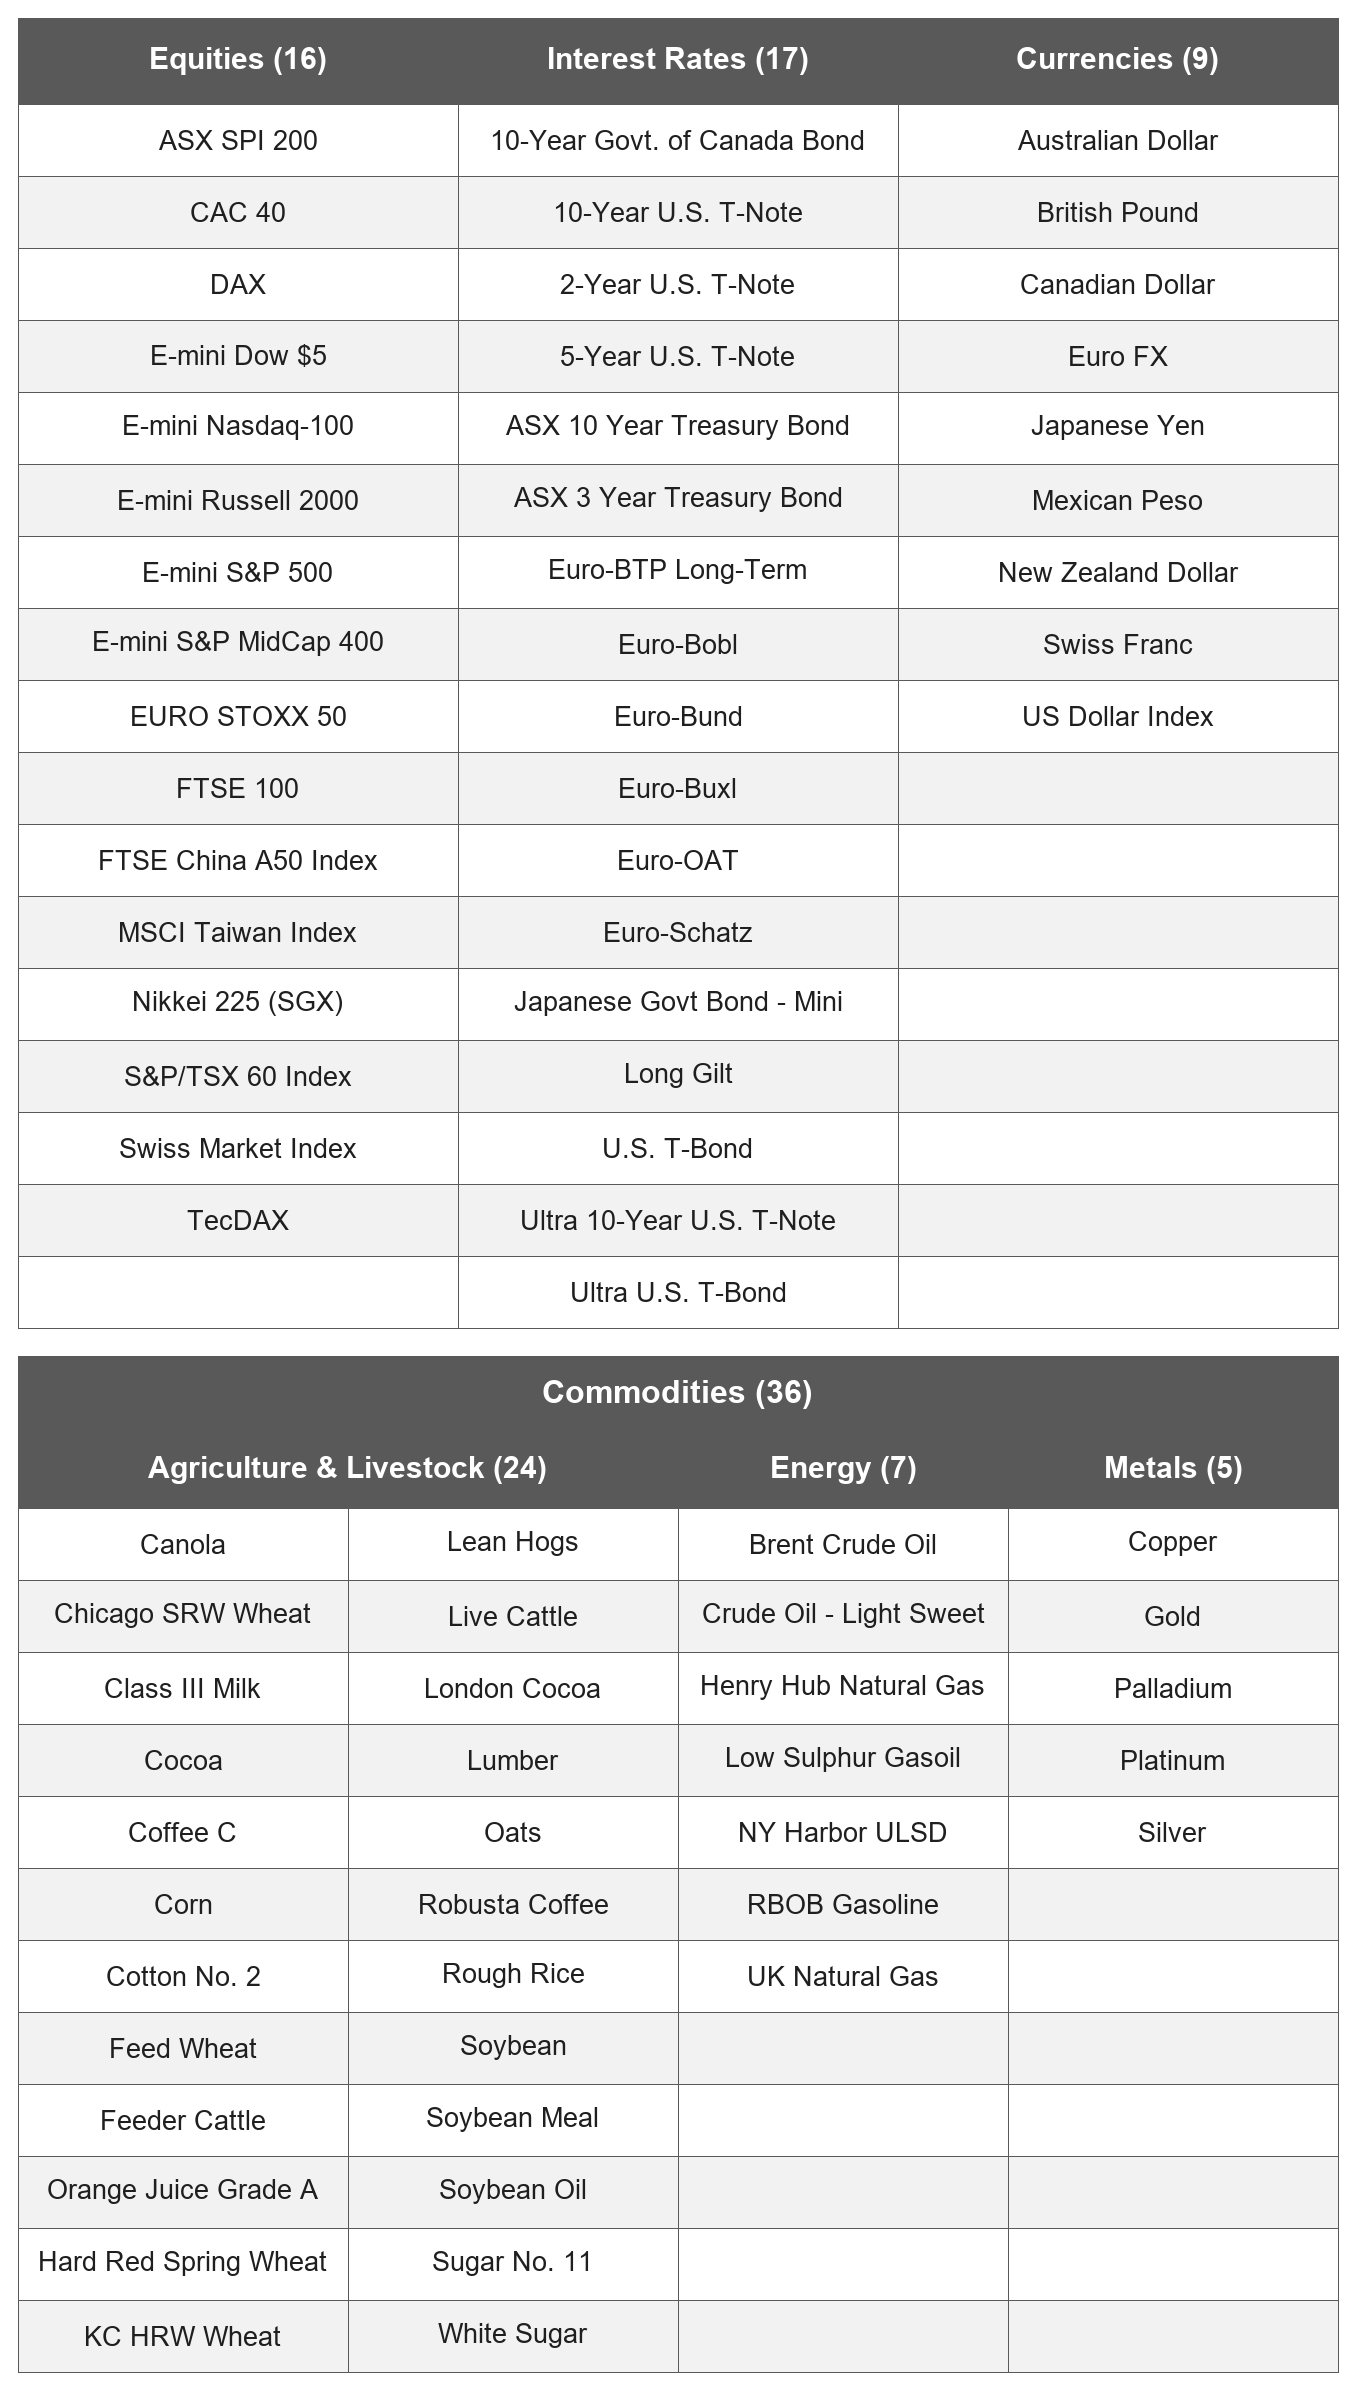
Our universe includes 78 futures across equities, interest rates, currencies and commodities, covering both U.S. and international markets and spanning more than 30 years of history, from January 1995 through July 2026.
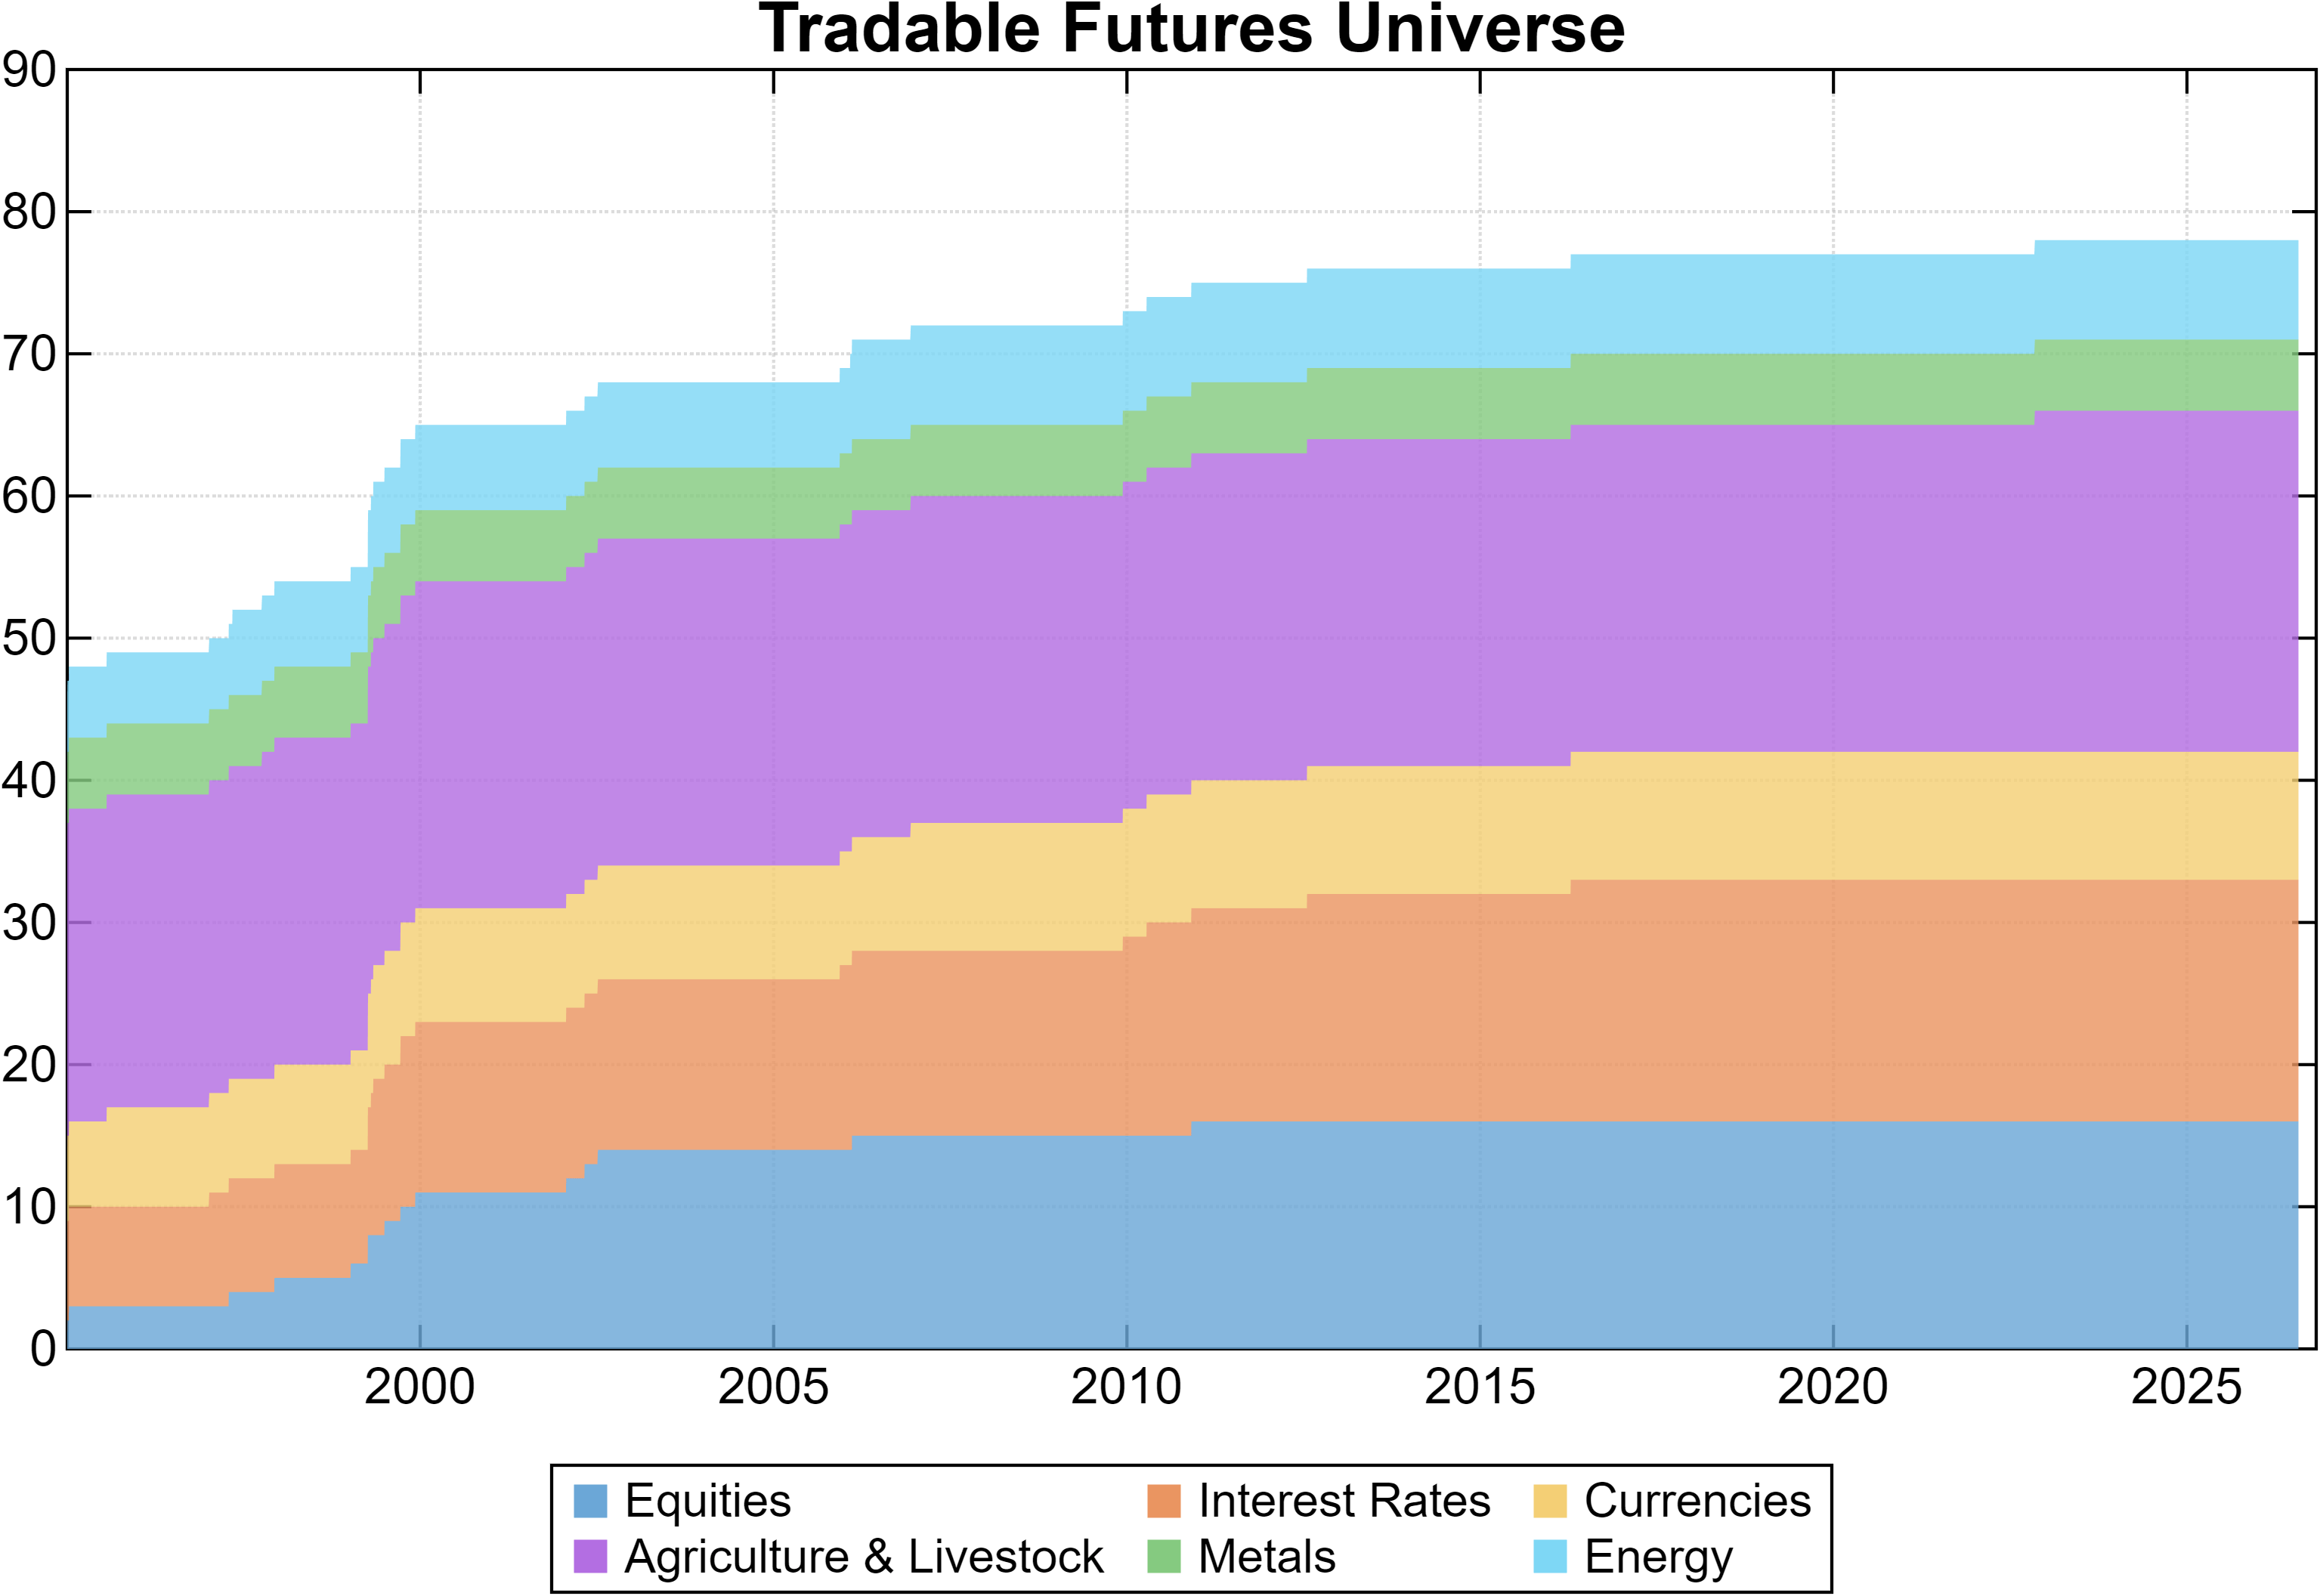
Notably, only 46 of these markets were tradable at the start of our sample, as illustrated in the figure below.
Trend Signal
Drawing on the work of Lempérière et al. in “Two Centuries of Trend Following”, we define our trend signal (S) by observing closing prices (P) relative to their 5-month exponentially weighted moving average (EWMA). Formally, for each market (i) at time t, the signal is given by:
As a result, S ordinarily takes one of two directional values: +1, indicating an uptrend, and -1, signaling a downtrend. It is 0, and therefore flat, only in exact-equality cases.
Volatility Estimates
The volatility of each futures contract (σi) is estimated as its median (absolute) daily P&L over a rolling three-month window, equivalent to ~63 trading sessions.
Note that we convert daily P&L fluctuations into US dollars (USD), consistent with the reporting currency of our baseline trend portfolio.
Other Assumptions
To approximate realistic operational workflows, we impose a one-day lag between signal generation and trade execution. Positions are then rebalanced daily to remain aligned with their target allocations.
Finally, all CTA returns and performance metrics are reported in excess of the risk-free rate and gross of transaction costs.
The Role of Capacity
With a generic trend-following strategy in place, we can now test whether concentrating trading activity in the most liquid contracts leads to lower risk-adjusted returns than a less constrained implementation.
To do so, we introduce two position-sizing policies: an equal-weighted approach (EW) that assigns each eligible contract an equal share of the specified risk budget, and a capacity-weighted approach (CW) which allocates more risk to contracts with greater estimated capacity (C).
CW is intended to reflect the liquidity constraints faced by ETF structures, whereas EW serves as a benchmark for a fully unconstrained and broadly diversified trend fund.
Formally, let R denote our risk budget, and let Nt be the set of tradable futures contracts at time t. If ri,t represents the share of the daily risk budget assigned to each contract (i), then the two position-sizing policies can be expressed as follows:
A Proxy for Capacity
Our capacity proxy is inspired by the framework presented by Quantica Capital in “The Footprint of Trend-Following”, one of their 2022 Quarterly Insights.
The core premise is that trend followers typically size positions inversely to estimated risk. Consequently, liquidity is best understood in risk-adjusted terms, as each market’s capacity to absorb volatility-scaled exposures.
In particular, we define a market as having high capacity (C) when its typical contract volume (V) is large relative to the position (Q) required to express a given amount of risk. Because Q is itself inversely proportional to our dollar volatility estimate (σ), it follows that:
Importantly, we use C only in relative terms, normalizing it either across the full eligible universe or within each sector, depending on the application. As a result, any common scaling factor, including AUM and the overall risk budget, cancels out. Consistent with our treatment of σ as a risk proxy, we specify V as the rolling 63-day median of each market’s daily contract volume.
Different Methods, Different Results…
Global Risk Budget
We start by setting a (daily) global risk budget equal to 1% of portfolio AUM, representing a unique pool of risk shared by all tradable futures markets.
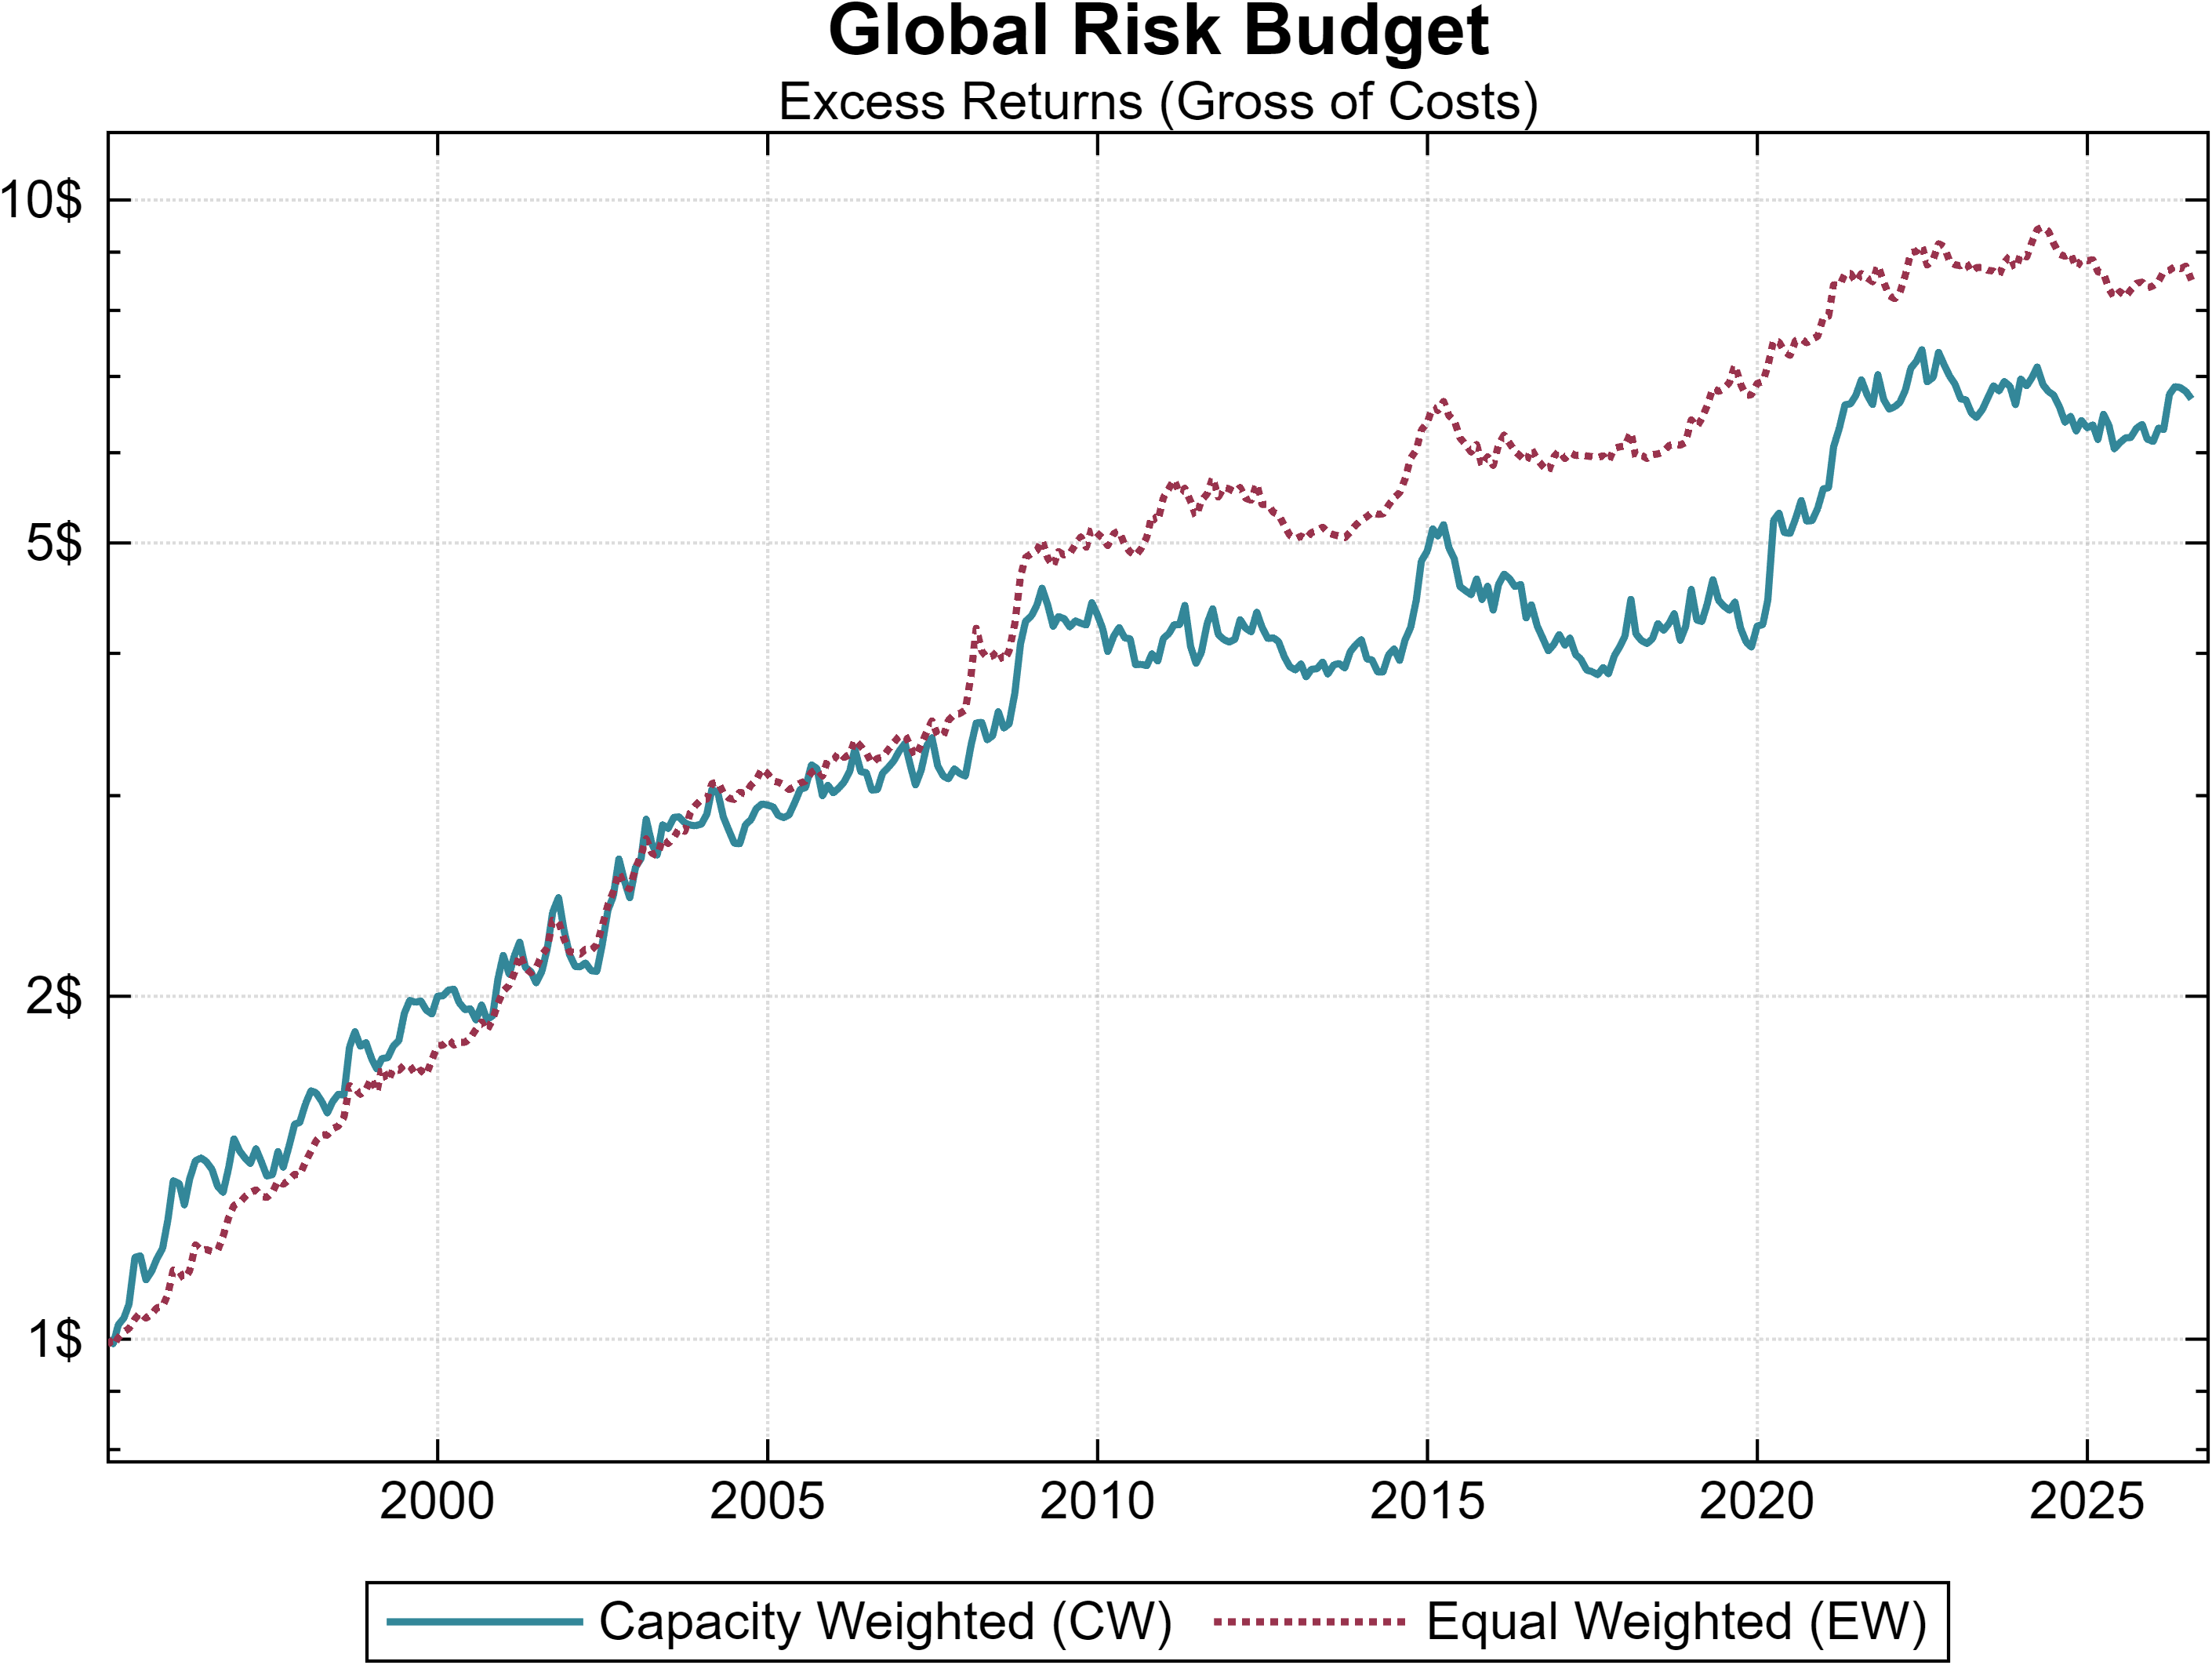
Under this approach, the equal-weighted risk policy produces a Sharpe ratio of 0.93, which is substantially higher than what we measure for the capacity-weighted variant (0.54).
These results emphasize the diversification benefits of allowing smaller, thinner markets to contribute meaningfully to portfolio exposure. By contrast, concentrating risk in the most liquid contracts reduces the diversification provided by many “niche” and somewhat idiosyncratic commodities, ultimately leading to lower risk-adjusted returns.
Yet, more experienced quants may have already noticed that these results are influenced by more than capacity alone. In the absence of sector constraints, the composition of the investable universe directly determines which groups receive larger risk allocations and which receive smaller ones.
Commodities, for example, account for 36 of the 78 contracts in the current universe and (under EW) are therefore allocated nearly half of the total risk budget. This naturally raises an important question:
Is it appropriate to let the number of available futures contracts within each sector dictate such a skewed distribution of portfolio risk?
Addressing this concern requires a more disciplined risk-budgeting framework before the equal-weighted and capacity-weighted approaches can be compared again.
Hierarchical Risk Budget
For instance, we can adopt a hierarchical risk policy under which equities, interest rates, currencies, and commodities each receive one quarter of the total daily risk budget (always fixed at 1% of portfolio AUM).
As highlighted in the following pie chart, within the commodities allocation, risk is divided equally across its three sub-sectors, Metals, Energy, and Agriculture & Livestock, so that each receives one third of the commodity risk budget.
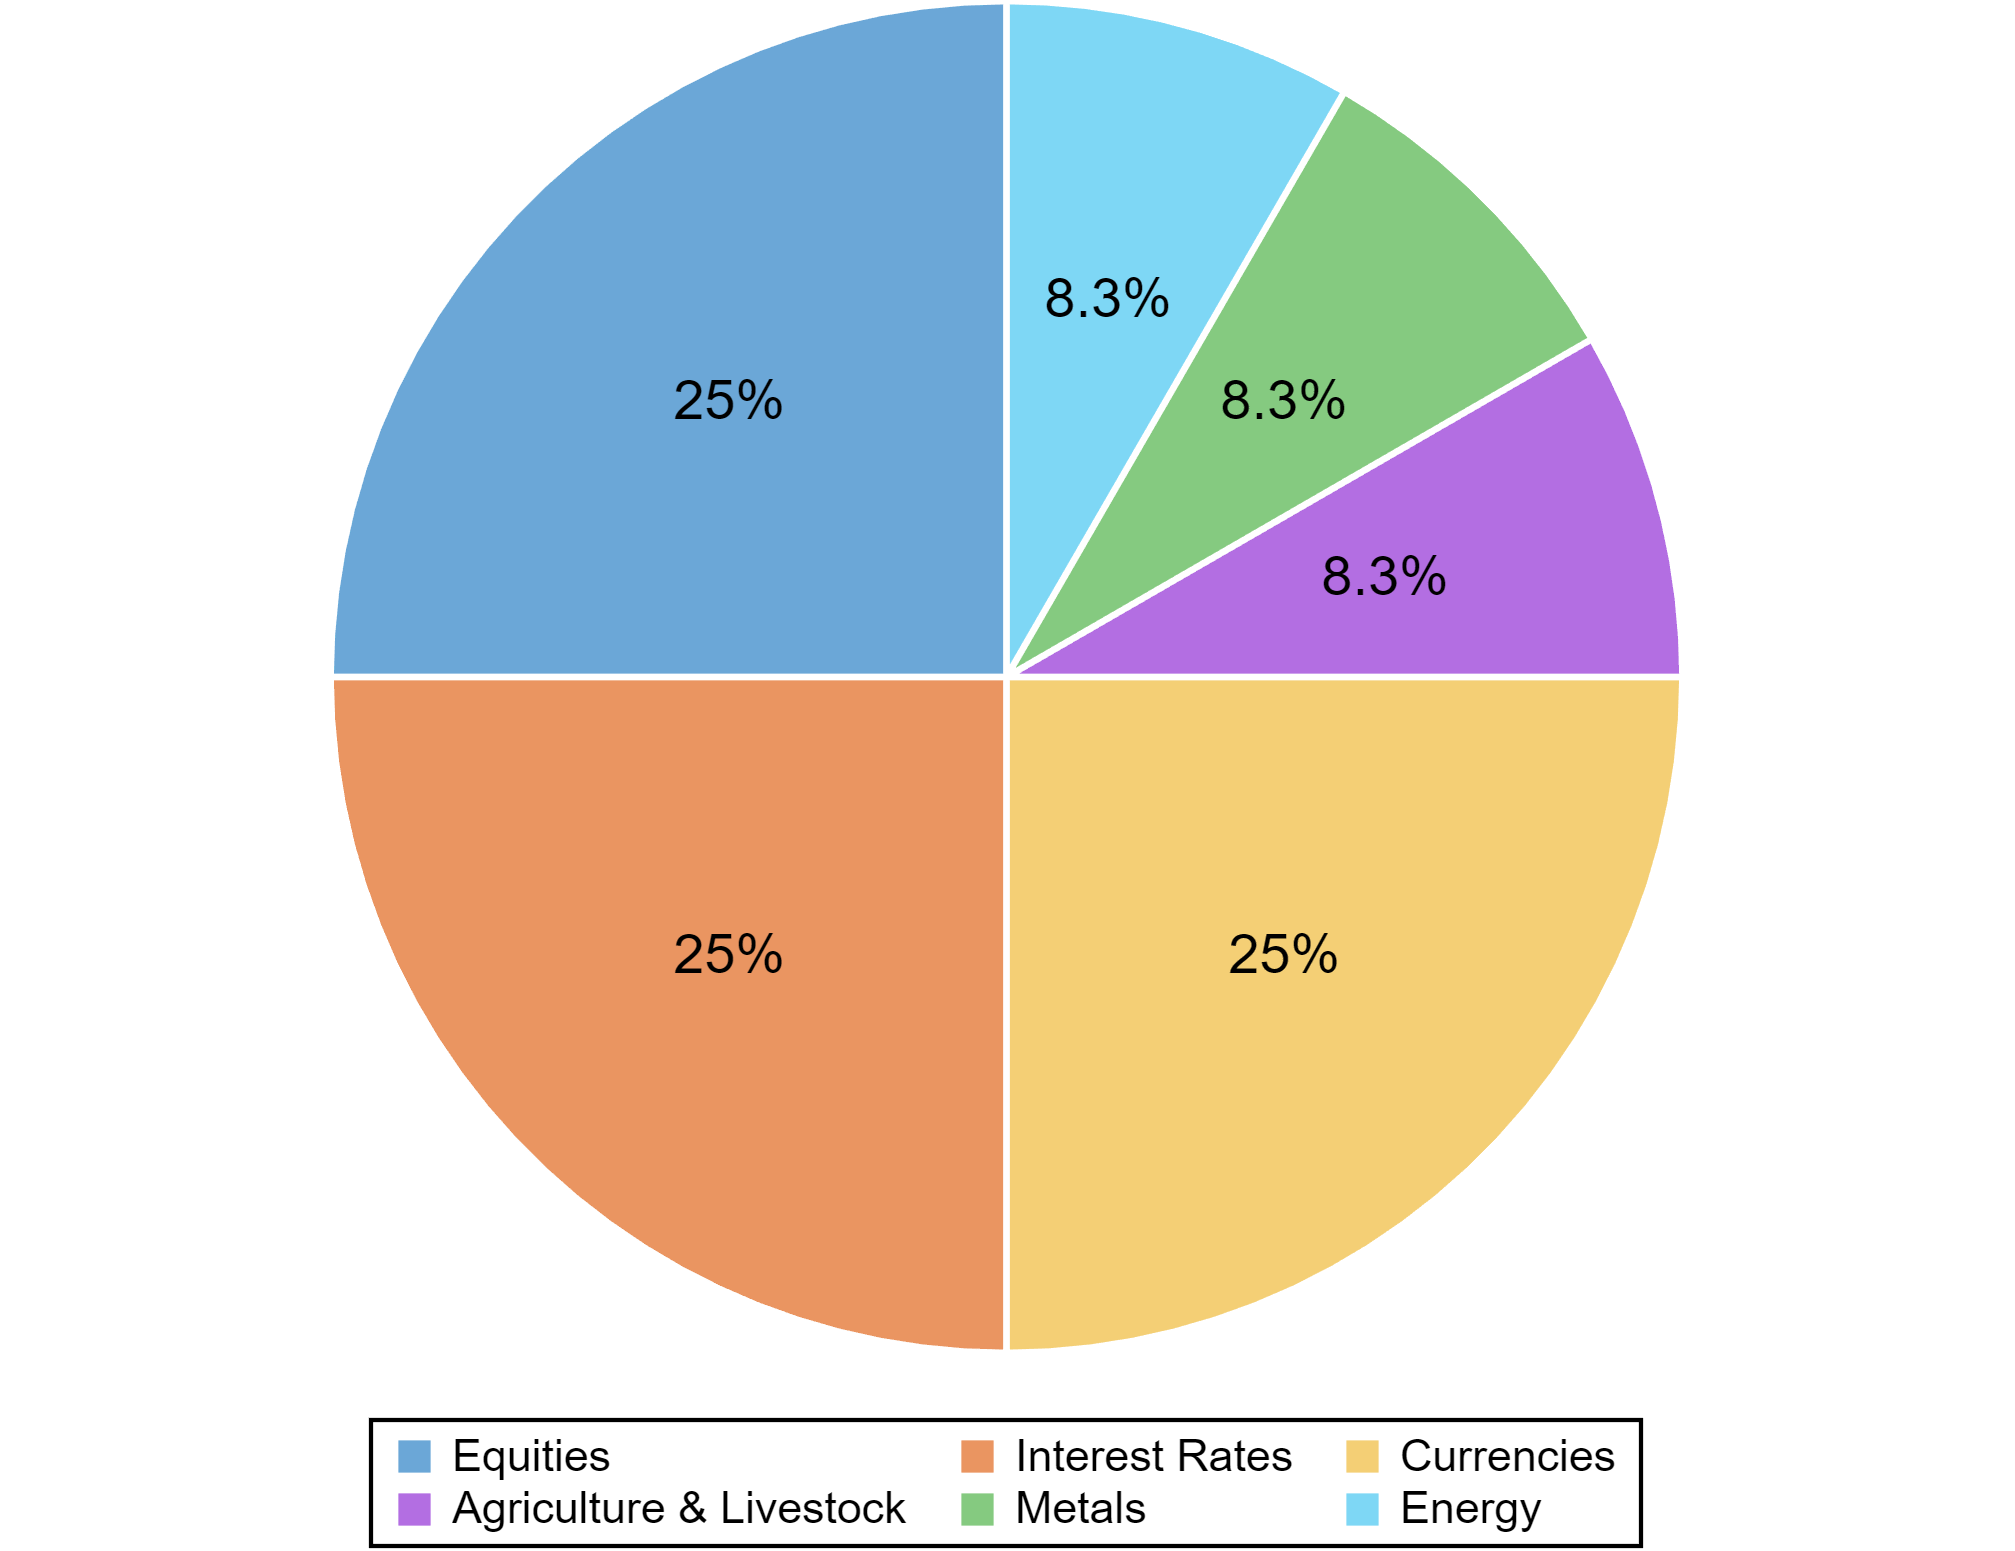
Crucially, under this approach, the four sector groups retain equal influence on portfolio risk, regardless of how many contracts each contains.
Having already compared EW and CW under a global risk budget, we now repeat the exercise within the new hierarchical framework. Accordingly, each sector’s risk budget is distributed either equally across its constituent markets (EW) or in proportion to each market’s relative capacity (CW).
In this setting, capacity is measured relative to peers within the same group rather than across the full investable universe.
As a result, a higher-capacity equity future (such as the E-mini S&P 500) may receive more risk than a less liquid equity contract, but it cannot draw risk away from commodities, interest rates, or currencies. Likewise, the large number of agricultural markets can no longer dominate overall portfolio risk.
The hierarchical structure therefore preserves diversification across economic groups while allowing capacity weighting (CW) to reflect the implementation constraints faced by ETFs.
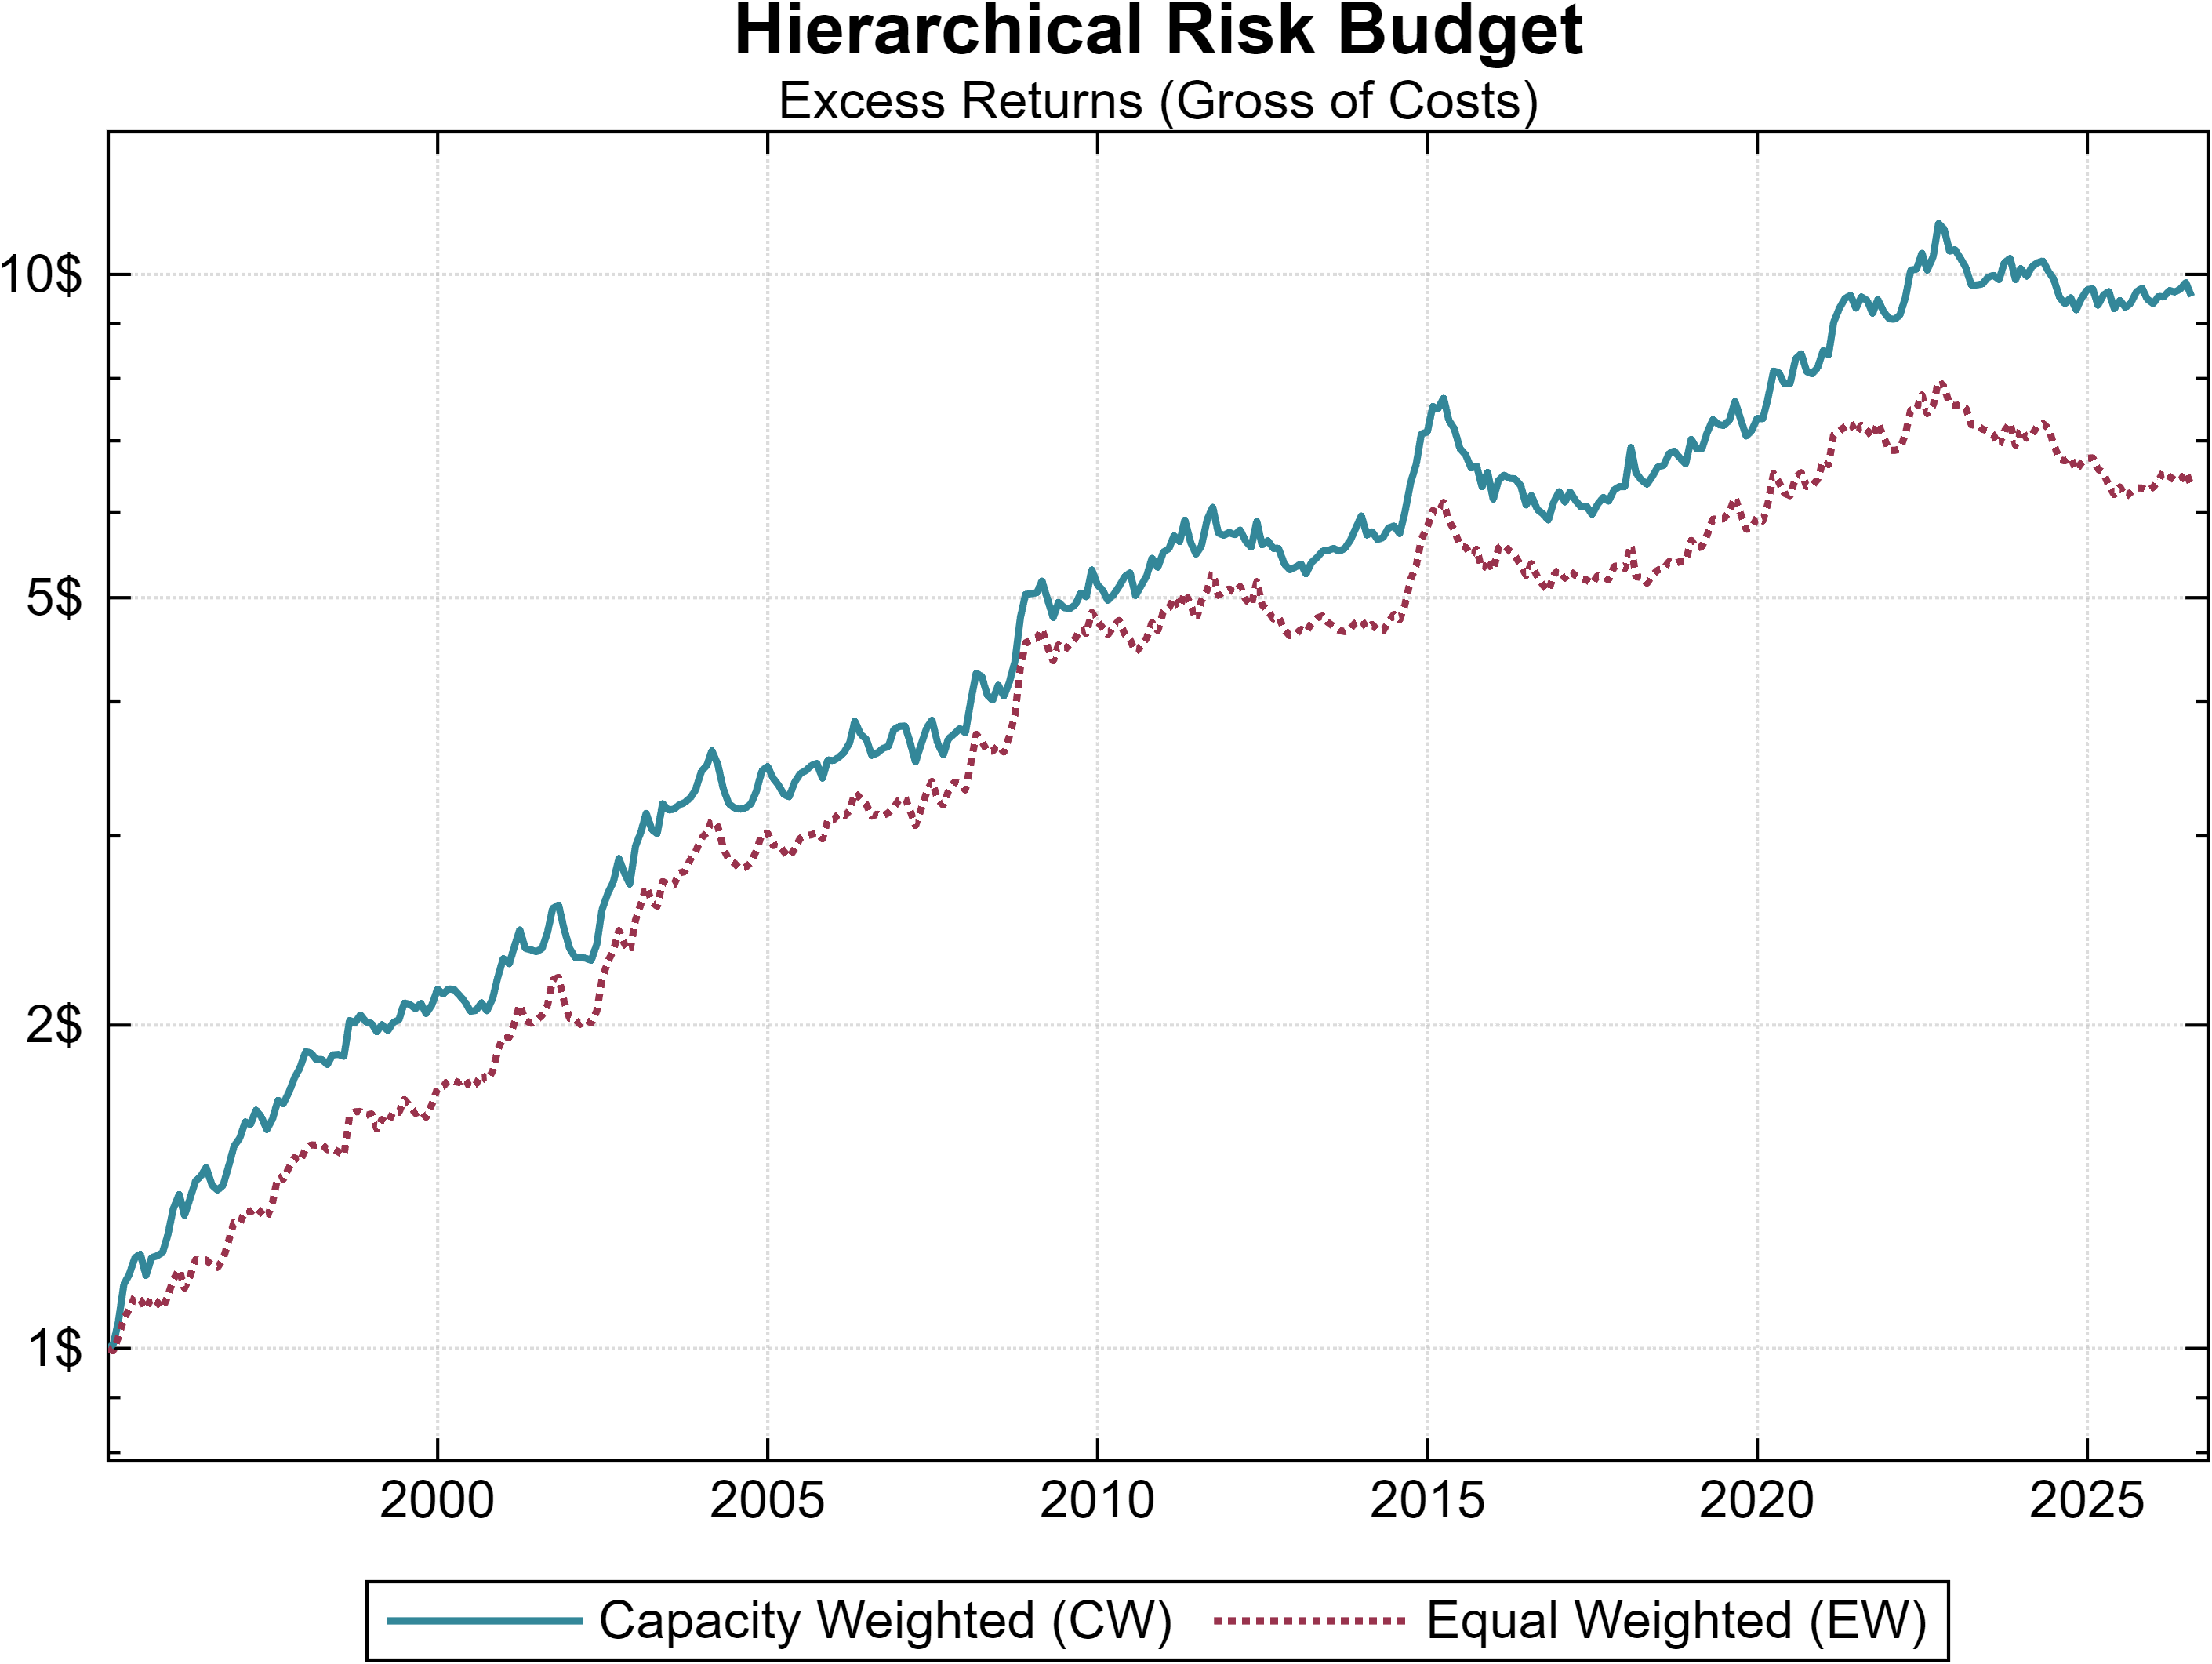
This time, the picture changes: EW records a Sharpe ratio of 0.69, compared with 0.71 for CW, leaving the two approaches essentially on par.
Taken together, the two experiments suggest that capacity constraints have limited impact on risk-adjusted returns, provided they do not materially alter the portfolio’s underlying economic composition.
A broad investment universe offers the greatest diversification benefits when its smaller, less correlated markets (primarily commodities in our case) are allowed to contribute substantially to the portfolio’s risk profile.
By contrast, once sector exposures are controlled at the top level, a more scalable, capacity-weighted implementation can still deliver risk-adjusted returns comparable to those of its equal-weighted counterpart.
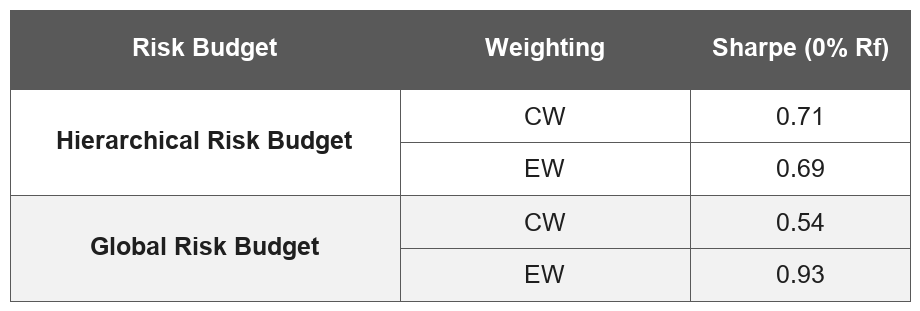
Results remain directionally unchanged when positions are sized at entry and contracts are held fixed until the trend signal switches state. Gross Sharpe ratios are 0.55 (CW) and 0.87 (EW) under GRB, and 0.63 (CW) and 0.61 (EW) under HRB. Relative to daily rebalancing, all are lower except GRB-CW, which rises marginally from 0.54 to 0.55, leaving the ordering and conclusions unchanged.
This modest deterioration in risk-adjusted returns is consistent with the findings of our prior work on sizing trend trades.

How About Diversification?
As a final test, we overlay two of our trend programs on a fully invested, passive allocation to SPY. Each portfolio is then rebalanced monthly to maintain exposures of 100% to SPY and 100% to the selected trend return stream.
This capital-efficient overlay belongs to the portable-alpha tradition and is now commonly identified as Return Stacking®, a term popularized by Rodrigo Gordillo, Corey Hoffstein, and Adam Butler in their work on capital-efficient portfolios.
We select the best-performing portfolio under each risk-management framework, global and hierarchical. This leaves us with an equal-weighted trend under a global risk budget (CTA1), and its capacity-weighted counterpart implemented within a hierarchical risk framework (CTA2).
In our prior tests, CTA1 emerged as the stronger risk-adjusted alternative, with a Sharpe ratio of 0.93, compared with 0.71 for CTA2. Now, we shift the focus from standalone performance to the diversification benefits each strategy provides when overlaid on a large-cap equity portfolio.
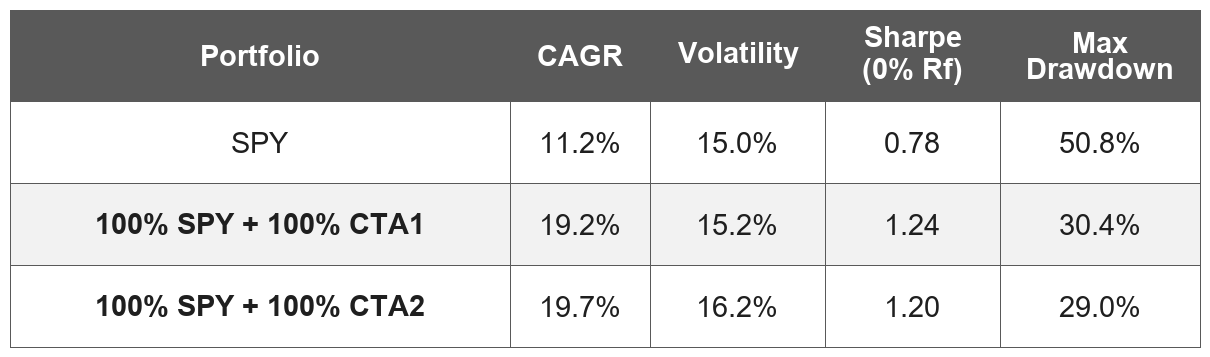
As shown in the table above, the empirical diversification benefits of the two strategies become much more similar once they are combined with equities.
SPY alone delivers a Sharpe ratio of 0.78 and a maximum drawdown of 50.8%: adding CTA1 improves these figures to 1.24 and 30.4%, respectively, while introducing CTA2 produces a Sharpe ratio of 1.2 and a slightly lower maximum drawdown of 29%.
Although the diversification benefits of adding CTA exposure “on top” of equity beta are empirically observable, they should not be viewed as guaranteed, insurance-like protection. Trend portfolios may still be long equities when markets begin to fall, amplifying risk during the initial phase of a decline rather than mitigating it.
We think another Quantica Capital quarterly insight, “Trend-Following and Risk Factor Diversification in 2022 and 2023: A Tale of Two Extremes,” helps explain why our more scalable, capacity-weighted variant remains such an effective diversifier to SPY.
Quantica finds that trend following’s strongest years have typically been driven by a small number of independent risk factors, as broad macro shocks generate persistent trends across markets. In these regimes (which have sometimes coincided with major equity drawdowns, such as in 2008 and 2022), concentrated investment universes spanning the main asset classes can compete effectively with much more diversified ones.

Our results appear aligned with this view: although CTA2 posts a lower standalone Sharpe, it enhances a passive allocation to equities essentially as much as CTA1.
Still, as Quantica notes, a broader universe is better positioned to capture diffuse, market-specific trends and has historically performed better over longer horizons, consistent with CTA1’s higher Sharpe ratio.
Conclusion
Taken together, our evidence suggests that ETFs can be both effective and efficient vehicles for delivering CTA-like exposure, even when restricted to deeper, more liquid futures markets.
Under a hierarchical risk budget, allocating more risk to higher-capacity markets did not materially impair either absolute or risk-adjusted performance of our trend program.
The same conclusion holds when trend portfolios are “stacked” on top of static equity beta: although the capacity-weighted program (CTA2) exhibits a lower standalone Sharpe ratio, it delivers nearly the same improvement in overall portfolio performance as its equal-weighted counterpart (CTA1).
If anything, this comparison may be conservative, as we impose no additional cost penalty on thinner markets. Net of such costs, the balance could tilt modestly toward the more liquid, ETF-style implementation. Our analysis also focuses on the underlying models rather than product economics; incorporating management and performance fees could therefore be a natural subject for a follow-up article.
Ultimately, whether one favors a broad, traditional program with access to niche markets or a liquid vehicle focused on deeper ones, we believe the final message remains the same: trend following and CTAs deserve a place inside traditional portfolios, perhaps now more than ever.
If you found this article useful, feel free to leave a comment or contact us by direct message or at info@concretumgroup.com.

Research Transparency Statement
Every research idea, hypothesis, methodology, dataset, code, backtest, analysis, and conclusion presented in this article was independently developed by the Concretum Group research team. Artificial intelligence tools were used as productivity assistants to support the preparation of the final manuscript, including language refinement, grammatical review, and, where appropriate, the creation of tables, figures, and other visual elements. All research decisions, analyses, interpretations, and conclusions remain entirely those of the authors.
Disclaimer
This publication is provided by Concretum Group for informational, educational, and research purposes only. It does not constitute investment, financial, legal, or tax advice, nor a recommendation to buy or sell any security, instrument, strategy, or investment product. All investments involve risk, including possible loss of principal. Past performance, backtested performance, and historical analysis are not reliable indicators of future results. Readers should conduct their own research and consult qualified professionals before making investment decisions.
Full disclaimer: https://concretumgroup.com/disclaimer/